I am Aryan Ayyar, Fellow-in-Residence at Manipal Academy of Higher
Education. My work combines rational-expectations and
general-equilibrium theory, asset pricing, market microstructure,
and high-frequency empirical finance.
A price can reveal value without revealing the cost of unwinding a position. In a Kyle-style model with staggered execution, a prime broker uses order flow and its client’s order to forecast remaining informed trading. Markets with the same price-update variance can have different margin sensitivity to signed order-flow surprises; binding requirements induce forced position reductions. The model focuses on the liquidity and closeout-execution component of margin.
Reframes FIFO priority as state-contingent adverse-selection
exposure, linking fill toxicity, cancellation, hidden effective
rank, and Kyle / Back information states.
Studies how information, liquidity pressure, and trend feedback shape
return covariance across horizons. Within the model, two adjustment
rates permit at most one sign change; Indian-equity patterns provide
descriptive evidence. Revised 24 September 2026.
The Exact Obstruction to Jamshidian's Decomposition in Multifactor Affine Models
2026
+
Characterizes exactly when Jamshidian's decomposition survives in
multifactor exponential-affine models: bond loadings must lie on a
common positive ray. Near that boundary, projected one-factor
strikes yield an upper bound with explicit error control.
Investor Preferences Under Uncertainty and the Cross-Country
Green Bond Premium
2026
+
Submitted to Finance Research Letters. Uses 417 matched green
bonds across 30 countries to study how long-term orientation and
uncertainty avoidance shape greenium heterogeneity.
In a price-time-priority market, an order ahead in the queue executes more often but can earn less. In a limit order book where dealers cancel and resubmit at random times, we construct an equilibrium in which an order fills more often than the one behind it yet earns less, while every dealer profits from supplying liquidity. Dealers also pay to surrender a valuable place in the queue to avoid being moved up into a worse position. A two-round extension adds learning, repricing and repeated informed trading. Version 2, October 2026.
A public dashboard built from raw Nasdaq TotalView-ITCH order-level
data: visible depth, top-of-book motion, execution bursts, cancel
waves, and liquidity droughts.
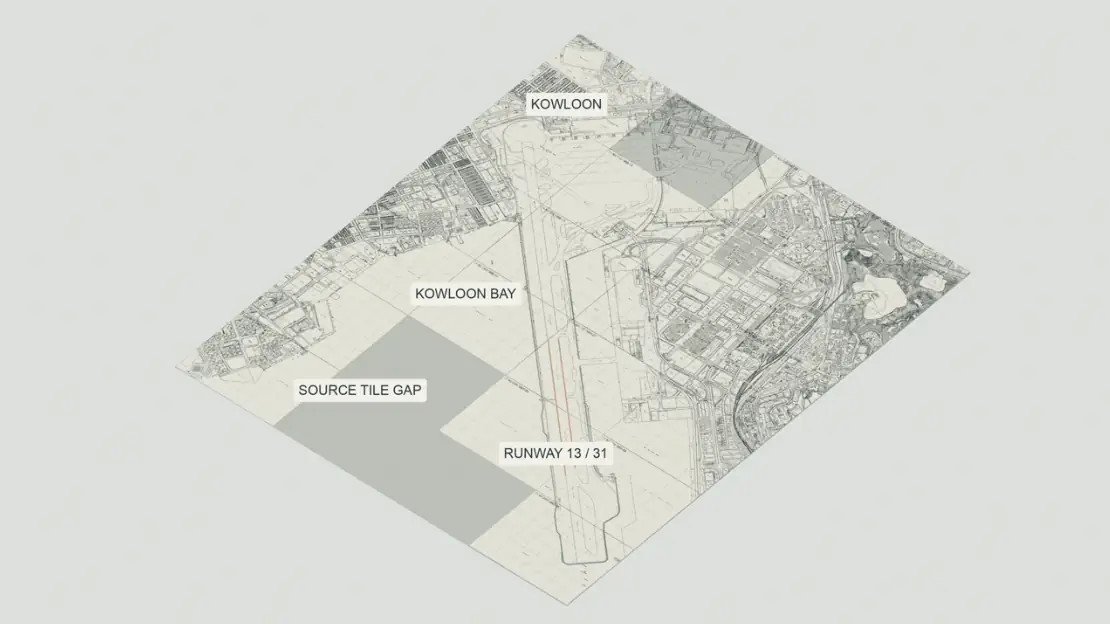
A personal study of Hong Kong’s former airport, bringing together
historical maps, aerial photographs and flight dynamics to explore
how a turn, descent, touchdown and full stop fit into one
constrained trajectory.
Kai Tak and Kowloon, assembled from survey-map editions dated 1986–1993. Missing source coverage remains visible.
Map sources and credit
Source data: Lands Department, Government of the Hong Kong Special Administrative Region; CSDI Portal and DATA.GOV.HK. Government and relevant organisations retain intellectual-property ownership. Reconstruction and rendering: Aryan Ayyar. Data and derivatives are supplied as-is; no Government endorsement.
The illustrated whitepaper follows the historical evidence and
two synthetic landing constructions under explicit assumptions.
This is ongoing research, not operational flight guidance or a
claim of historical obstacle clearance or global optimality.